The S&P 500's worst day since April 2025 was not a verdict on artificial intelligence. It was a verdict on how the build-out is financed. We trace the shift from an equity story to a credit story, and what it means for concentration risk and portfolio construction.
The Federal Reserve raised rates in September for the first time in three years, and October's hotter-than-expected inflation print keeps a December hike on the table. We assess the policy dilemma on both sides of the Atlantic and what it means for duration, the dollar and equity risk.
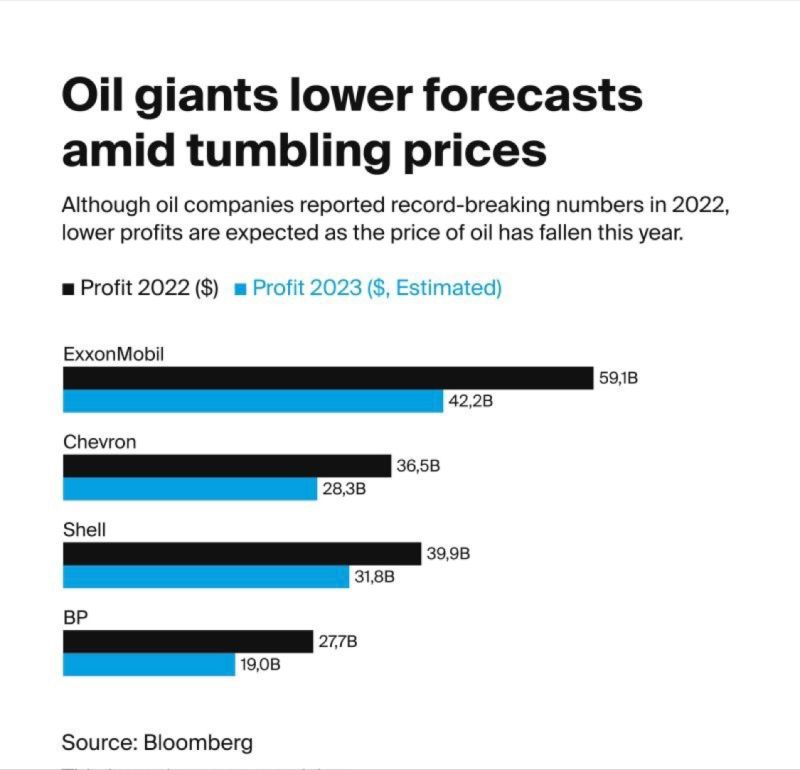
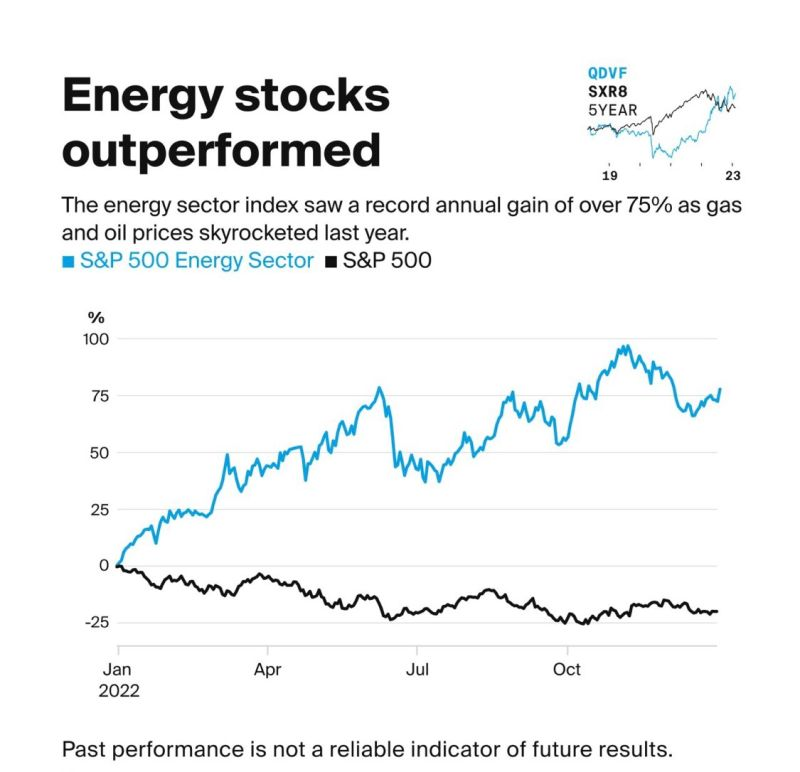
Brent has fallen from four-year highs in late October to the low $90s as markets price a negotiated end to the Iran war after the U.S. midterm elections. We assess how much risk premium has really left the oil price, what remains unresolved, and why the distribution of outcomes is still unusually wide.
Brent near $88 and a naval blockade that has turned the world's most important chokepoint into a bargaining chip. We assess the geopolitical trajectory of the US–Israel–Iran conflict and quantify its transmission into inflation, rates, currencies and cross-asset risk premia.
Advanced-economy debt-to-GDP ratios have crossed critical thresholds. We examine why fiscal dominance is no longer an emerging-market phenomenon - and what it means for systematic fixed-income and equity strategies.
Modern markets are vulnerable to liquidity shocks that propagate from microstructure frictions to macro-level drawdowns. We examine the mechanisms - and how systematic strategies can measure, monitor, and mitigate them.
With the FOMC having delivered its first rate cut of the cycle and signalling a measured easing path into 2027, the term premium, the dollar, and the equity risk premium are repricing in tandem. We dissect what has actually changed - and what hasn't.